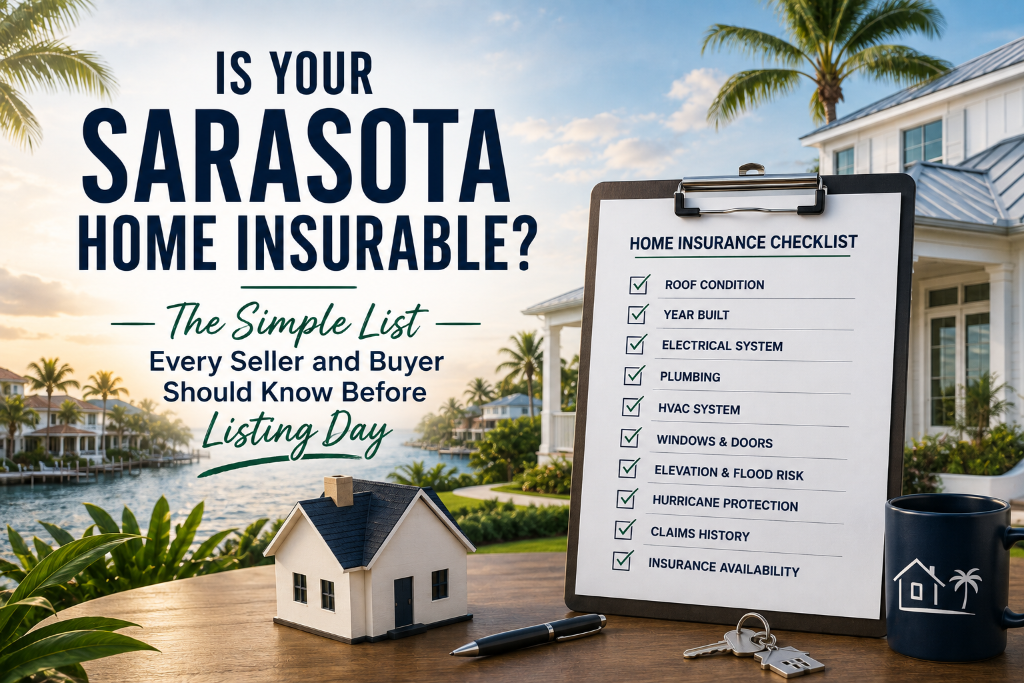
Is Your Sarasota Home Insurable? The Simple List Every Seller and Buyer Should Know Before Listing Day
In 2026 Sarasota real estate, if a home isn't insurable it isn't sellable to a financed buyer. Here's the roof, electrical, plumbing, HVAC, wind, flood, and condo checklist I run through with every seller and buyer.
Is Your Sarasota Home Insurable? The Simple List Every Seller and Buyer Should Know Before Listing Day
By Kelly Fullick, REALTOR® · Coldwell Banker Realty · Sarasota native
Here is the hardest truth about Sarasota real estate in 2026:
If a home isn't insurable, it isn't sellable — at least not to a financed buyer.
This post is the simple checklist I run through with every seller before we go live and with every buyer before they write an offer. If you're selling, this is why a pre-listing inspection is worth every dollar. If you're buying, this is what to ask about before you fall in love with the address.
Why insurability decides everything now
Florida's insurance market has been resetting since 2022. Multiple carriers left the state, wind-mitigation and roof-age rules tightened, and reforms shifted more risk onto homeowners. In 2026, three realities drive every transaction here:
- Financed buyers must have bindable insurance. No lender closes without a bound homeowners policy. If a private carrier declines and Citizens declines, the deal is dead unless the buyer pays cash.
- Citizens is not a fallback anymore. Under Florida Statute §627.351(6), Citizens must decline to write a policy if any admitted private carrier offers comparable coverage within 20% of the Citizens premium. That means a home has to fail out of the entire private market first, and then still meet Citizens' underwriting rules.
- Insurance and appraisal are now the two biggest deal-killers in Sarasota — bigger than financing or inspection issues, in my experience over the past 18 months.
For deeper context on the market itself, see Sarasota Hurricane & Home Insurance Guide and Why Some Sarasota Homes Cost 10× More to Insure.
The simple list: what makes a Sarasota home uninsurable (or nearly so)
I keep this list on my phone. It maps to the two inspections carriers actually rely on — the 4-point inspection (roof, electrical, plumbing, HVAC) and the wind mitigation inspection (roof, openings, straps).
1. The roof
The single biggest reason Sarasota homes fail insurability.
- Shingle roof older than 15 years — most private carriers won't write; some tighten at 20
- Tile roof older than 25-30 years or with cracked/loose/missing tiles
- Metal roof older than 30-40 years or with rust, lifting, or panel separation
- Flat/modified bitumen roof older than 10-15 years — the strictest category
- Any roof with less than 3-5 years of useful life remaining on inspection, regardless of age
- Active leaks, staining, or visible damage on the underside from the attic
- Missing or improperly nailed shingles, exposed underlayment, rusted flashing
- No wind-mitigation form on file (or one older than 5 years)
2026 update — Florida SB 808 / HB 815 (effective July 1, 2026): insurers may no longer refuse to issue or renew a policy solely because of roof age if the roof has documented remaining useful life. The word "solely" is doing a lot of work here — carriers can still decline for other reasons. Under FS 627.7011(5), any roof under 15 years old cannot be declined for age alone, and at 15+ years a passing inspection showing 5+ years of remaining life defeats an age-only refusal.
Citizens' hard line: asphalt shingle, tile, and metal roofs must be under 25 years; flat roofs under 15 years, with a possible case-by-case exception for a documented 5+ years of remaining life.
2. The electrical panel
The number-two reason for a failed 4-point.
- Federal Pacific Electric (FPE) Stab-Lok panel — almost universally declined
- Zinsco (or Sylvania-Zinsco) panel — same
- Challenger panel — same
- Aluminum branch wiring without approved COPALUM or AlumiConn connectors
- Knob-and-tube wiring (rare in Sarasota but present in some pre-1950 homes)
- Double-tapped breakers, missing knockouts, exposed bus bars
- 60-amp service in an all-electric home
- Cloth-insulated wiring or Romex without ground
3. The plumbing
- Polybutylene ("poly") plumbing — almost universally declined; needs full replacement to become insurable
- Cast iron drain lines older than 40-50 years with documented failures
- Galvanized supply lines — increasingly declined
- Active leaks, corrosion, or repeated repairs flagged on the 4-point
- Whole-home water heater older than 12-15 years or missing an expansion tank in a closed system
4. The HVAC
- HVAC system older than 15-20 years — many carriers require replacement or a 5-year-life letter
- Missing or non-functioning system at time of inspection
- Rust, corrosion, evidence of leaks on the air handler or condenser
- Non-permitted installation with no closed permit in the county record
5. The four-point-passing home that still fails on windstorm
Even a perfectly maintained inland home can fail wind underwriting if:
- No wind mitigation form (OIR-B1-1802) on file, or the form is older than 5 years
- No opening protection — no impact windows, no accordion or panel shutters, no fabric-code compliant shutters. Citizens requires opening protection to write in wind-prone zones
- Roof-to-wall connections are toe-nailed instead of clipped, single-wrapped, or double-wrapped
- Gable-end bracing absent on a home with gable roof design
- Home built pre-2002 (before Florida Building Code updates) with no documented upgrades
6. Location, elevation, and flood
- Special Flood Hazard Area (SFHA) designation — Zone AE, VE, A, or V — triggers a mandatory flood insurance requirement for any financed purchase, and Citizens' phased flood-insurance mandate takes full effect January 1, 2027
- Base Flood Elevation (BFE) below finished floor — insurable but expensive; flood premium can run $3,000-$12,000+ per year
- Barrier island location — some carriers won't write within a set distance from the coast (varies by carrier and wind speed contour)
- Repetitive-loss property — historical NFIP claims can spike or block coverage
For the neighborhood-level view, see Sarasota Flood Zones and Elevation and Sarasota Home Insurance Costs by Neighborhood.
7. Condo-specific insurability killers
Condos are their own world. The unit-owner HO-6 policy is often the easy part — the building's master policy and structural compliance are what determine whether any lender will finance in the building at all.
- No completed Structural Integrity Reserve Study (SIRS) under Florida Statute 718.112(2)(g) — initial deadline was December 31, 2024
- No completed Milestone Inspection under Florida Statute 553.899 — required at 30 years of building age, 25 years within 3 miles of the coast
- "Unsafe structure" designation or open recertification failure — kills most private financing and now increasingly restricts Citizens condo policies
- Association hasn't funded the SIRS reserves — reserves for SIRS items can no longer be waived starting with budgets adopted on or after December 31, 2024
- Master policy with deductibles above lender caps — Fannie/Freddie/FHA/VA all have max deductible rules
- Open litigation, uninsured wind claims, or major deferred maintenance — buildings fail Fannie/Freddie condo review ("non-warrantable")
For the full condo picture, see The Sarasota Condo Market in 2026.
8. The other quiet dealbreakers
- Unpermitted work — additions, screen rooms, pool cages, electrical, or plumbing without closed permits show up in property records and can void coverage on a claim
- Prior claim history on the CLUE report — 3 or more claims in 5 years is often a hard decline
- Open Code Enforcement violations — hurricane debris, unpermitted structures, illegal STR operation
- Aluminum branch wiring without pigtailed connectors (repeats from electrical for emphasis — it's that common in 1970s Sarasota homes)
- Woodstove, unvented fireplace, or non-code chimney
- Trampoline, above-ground pool without a fence, or dog on a restricted-breed list — liability exclusions
- Vacant home over 60 days — most carriers require a vacancy endorsement or the policy lapses
What can be cured before listing (the seller playbook)
Not every problem is fatal. This is the honest, category-by-category read on what's fixable, and what isn't.
Curable — usually worth doing before listing
| Issue | Realistic cost range | Difficulty | Impact on saleability |
|---|---|---|---|
| Old shingle roof (over 15 years) | $18,000-$45,000 | Medium (2-4 weeks with permit) | High — opens up almost every private carrier |
| FPE / Zinsco / Challenger panel replacement | $2,500-$5,500 | Easy (1 day + permit close) | High — removes an automatic decline |
| Polybutylene repipe | $6,000-$18,000 | Medium (1-2 weeks) | High — removes an automatic decline |
| Aluminum wiring pigtailing (COPALUM/AlumiConn) | $2,500-$8,000 | Easy | Medium — makes some carriers writable |
| HVAC replacement (15+ years) | $8,000-$16,000 | Easy (1-3 days) | Medium — expands carrier options |
| Water heater replacement with expansion tank | $1,500-$3,500 | Easy | Medium |
| Wind mitigation inspection ($100-$200) | $100-$200 | Easy | High — often unlocks discounts and eligibility |
| Closing out open permits | $200-$2,500 | Easy to medium | Medium — clears financing hurdles |
| Installing impact windows / accordion shutters | $8,000-$50,000 | Medium (2-4 weeks) | High — dramatic wind-premium reduction |
| Clearing an active leak or repairing flashing | $500-$3,500 | Easy | Medium — removes a 4-point flag |
Curable — but only sometimes worth it
| Issue | Notes |
|---|---|
| Tile roof at 25-30 years | If tiles are sound, a documented remaining-life letter from a licensed roofer + updated wind-mit form is often cheaper than replacement |
| Prior claim history on CLUE | Claims fall off the report after 5-7 years; time is the fix. Sometimes worth disclosing and marketing to cash buyers |
| Vacancy | Have Kelly's team stage or lightly furnish; keep utilities on; add a vacancy endorsement during listing |
Rarely curable pre-listing (price and market accordingly)
| Issue | Reality |
|---|---|
| Flood zone AE or VE with low BFE | Elevation cannot be changed cost-effectively for most homes. Market with elevation certificate + realistic annual flood premium disclosed |
| Barrier island wind exposure | Location can't move. Impact windows + Citizens or E&S carrier is often the play |
| Condo building without Milestone or SIRS | Association-level fix, not owner-level. Buyers pay cash or walk |
| "Unsafe structure" designation on a condo building | Kills financing entirely until the building repairs and re-inspects |
| Repetitive-loss NFIP property | Grandfathered subsidies erode with each claim; will need private-flood shopping |
| Underground fuel tank | Environmental phase-2 issues; case by case, often deal-killing |
| Sinkhole activity on record | Requires optional endorsement + full geotechnical clearance |
The pre-listing inspection playbook I use with every seller
This is the sequence that saves the deal. Skipping any step is where most Sarasota listings quietly break.
90-120 days before listing
- Full home inspection ($400-$650) — the same kind the buyer's inspector will run
- 4-point inspection ($75-$200) — the exact form the insurance carrier will read
- Wind mitigation inspection ($100-$200) — usually done same-visit with the 4-point
- Roof condition letter from a licensed roofer if roof is 15+ years — costs $150-$400 and can add years of insurability
- Get a real insurance quote on your own home through your agent or an independent broker. This tells you exactly what a buyer's quote will look like
30-90 days before listing
- Close out any open permits with the county — this is invisible until financing pulls the report
- Fix the easy insurability items — panel swap, water heater, HVAC service, small leaks
- Make the big call on roof, repipe, and windows — replace before listing or price accordingly. I help my sellers run the actual math on both paths
- Update CLUE report and clear any inaccuracies (yes, homeowners can dispute their own report through LexisNexis)
At listing
- Include the wind-mit form, 4-point results, and roof letter in the listing agent's disclosure packet
- Publish the insurance-carrier estimate range if it's favorable — this actively pulls buyers who have been burned by uninsurable listings elsewhere
- For condo listings: include the Milestone Inspection, SIRS, master policy declarations, and last three years of association meeting minutes
Under contract
- Confirm the buyer's insurance is bound by day 14-21 of the contract at the latest, or the deal will be surprised at closing
- Never let the buyer's insurance walk to Citizens as first choice — Citizens will only write if private carriers decline first, and Citizens has stricter roof/wind rules than many private carriers
For buyers: the six questions I ask before we make an offer
- How old is the roof, exactly? (Not "recent" — a permit number and date)
- Is there a current wind mitigation form on file?
- What panel brand is in the garage? (I've had buyers walk on FPE panels alone)
- Is there polybutylene, cast iron, or aluminum wiring in the disclosure?
- What's the flood zone, and is there a current elevation certificate?
- For condos: has the building completed its Milestone Inspection and SIRS, and are reserves funded?
I get real insurance quotes before the appraisal contingency expires — never after. If a home turns out to be uninsurable at a reasonable premium, we walk before losing earnest money.
The three-line summary I want you to remember
- Insurability is now the single most important thing about a Sarasota home. More than curb appeal, more than staging, more than the last listing photo.
- A pre-listing inspection is not a luxury — it's how sellers close on time and at price. The seller who inspects at day 90 wins. The seller who finds out on day 25 of a contract loses.
- The problems are knowable, and most are fixable. Roof, panel, plumbing, HVAC, wind mitigation, permits. That's the checklist.
If you're planning to sell a Sarasota home in the next 6 months, or you're looking at buying one, let's walk through the list together before anything is decided.
Want to talk through your specific situation?
I'm Kelly Fullick, a Sarasota native and REALTOR® with Coldwell Banker Realty. I help buyers and sellers make clear-headed decisions in the Sarasota/Manatee market — no pressure, just honest guidance.
📞 941-260-7770 📧 Kelly@kellyfullick.com 🌐 KellyFullick.com
Serving Sarasota and Manatee County.
This post is educational only and is not insurance, legal, or tax advice. Every insurance carrier's underwriting guidelines are set by that carrier and change over time. Verify specific eligibility with a Florida-licensed insurance agent, and always confirm building compliance directly with your condo association's board or property manager. Costs and thresholds are 2026 estimates for the Sarasota/Manatee market and vary by property, carrier, and neighborhood.
Sources: Florida Statute §627.7011 — Roof Age & Underwriting Restrictions; Florida House Bill 815 / SB 808 (effective July 1, 2026); Florida Statute §627.351(6) — Citizens Eligibility; Florida Statute §553.899 — Milestone Inspections; Florida Statute §718.112(2)(g) — Structural Integrity Reserve Study (SIRS); Citizens Property Insurance Corporation — Wind Loss Mitigation Guide (April 2026); Citizens Property Insurance — Flood Insurance Requirement; Florida OIR — Property Insurance Reforms.
See also on kellyfullick.com/blog: Sarasota Hurricane & Home Insurance Guide, Why Some Sarasota Homes Cost 10× More to Insure, Sarasota Flood Zones and Elevation, Sarasota Home Insurance Costs by Neighborhood, The Sarasota Condo Market in 2026, Money Mechanics 7 (Selling Sarasota Net Proceeds), and What Sarasota Buyers Overlook Most.
About Kelly Fullick
Kelly Fullick is a Sarasota-native Realtor with Coldwell Banker Realty. She specializes in helping out-of-state relocation buyers and Sarasota-area sellers with candid, education-first guidance. Kelly has closed 34+ transactions totaling over $17.7M across Sarasota and Manatee County since 2022, and holds a perfect 5.0-star rating on 25 Google reviews.
Ready to take the next step?
Let's Talk About Your Goals
Every situation is different. Schedule a no-pressure conversation with Kelly to get clear on your options.
941.260.7770
kelly@kellyfullick.com
Schedule a ConsultationMore from the Journal
Sarasota Real Estate Market Updates
What If You Could Take Your Mortgage Rate With You? A New Bill Could Change the Way Homeowners Move
Sarasota Real Estate Market Updates
The Sarasota Condo Market in 2026: Where They Are, What They Cost, and What Nobody Tells You About the Fees
Sarasota Real Estate Market Updates